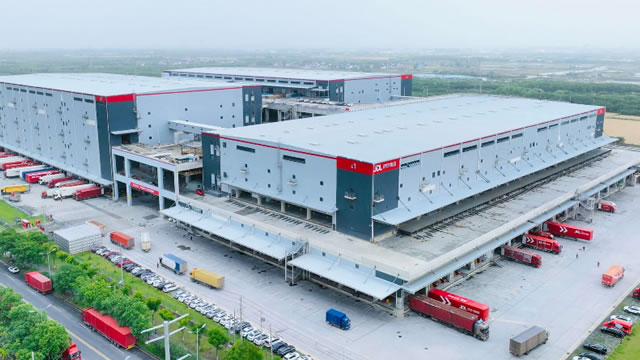
JD.com remains a Strong Buy, trading at an attractive valuation while it advances toward a potential re-rating. JD's Q3 revenue returned to growth, rising 3.5%, while its shift away from subsidy-heavy food delivery supports higher-margin growth. JD's European expansion combines Joybuy's delivery network with Ceconomy's >1,000 stores, while substantial cash supports elevated investment.